E-mail:
huhengzhao36@gmail.com
Mobile:
+86 137 3108 3388
English


English
English
English

The Egg Tray market outlook is shaped by rising poultry consumption, expanding egg production, and the move toward lower-cost, recyclable packaging across Africa, Asia, and Latin America. In practical terms, the market is tied to poultry packaging for emerging markets, molded pulp packaging for egg protection, and the economics of distributing fragile goods over long distances. For buyers, suppliers, and converters, the main question is not whether demand exists, but which regional growth drivers, material formats, and channel structures create the best entry points.
Egg Tray Market Outlook: Growth Drivers Across Africa, Asia, and Latin America is especially relevant because these regions are adding capacity at different speeds and with different packaging requirements. Asia remains the largest poultry production and egg consumption base, while Africa and Latin America are seeing faster structural gains in organized retail, feed availability, and intercity distribution. Rayee and similar machinery-focused suppliers are often evaluated by whether they can match these regional shifts with stable output, material flexibility, and predictable operating costs.
The egg tray market outlook refers to the expected demand, production, and procurement direction for egg trays over a defined forecast horizon, usually discussed in multi-year market studies. For 2026 planning, buyers typically evaluate egg packaging in terms of capacity growth, recycled fiber availability, tray format, and price sensitivity rather than a single global average. The outlook is strongest where poultry output is expanding faster than packaging infrastructure, which is why Africa, Asia, and Latin America are drawing more attention from producers and equipment buyers.
In simple terms, the egg tray market outlook is the forecast for how many trays will be needed, where demand will rise, and which material or format will sell best. It is driven by production volume, distribution distance, and packaging replacement cycles, not just by the number of hens. For export planners, the outlook is also tied to compliance, breakage reduction, and unit economics.
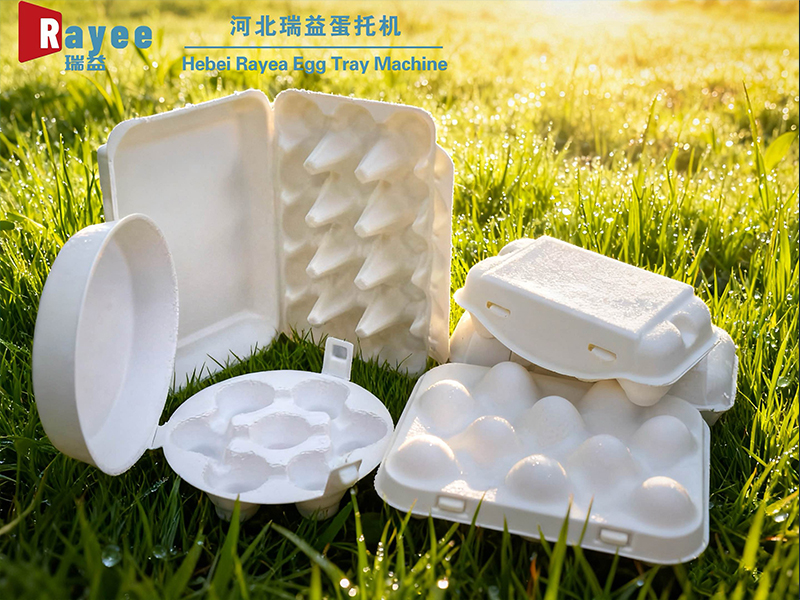
Global egg and egg packaging forecasts are usually assessed over a 5- to 10-year horizon because tray demand tracks poultry expansion, urbanization, and packaged food sales. Across the broader egg packaging category, growth is typically segmented by material (recycled paper pulp, molded fiber, plastic, and foam alternatives), product format (6-cell, 10-cell, 12-cell, 30-cell, and custom counts), and application (farm packing, wholesale distribution, retail cartons, and export handling). In most developing markets, molded pulp remains the reference format because it balances cost, stacking performance, and shock absorption.
| Segment | Common Formats | Typical Procurement Logic | Market Implication |
|---|---|---|---|
| Material | Molded pulp, recycled paper, plastic | Cost control and recyclability | Pulp leads where fiber supply is available |
| Product format | 6/10/12/30-cell trays | Transport density and egg size | 30-cell trays suit wholesale handling |
| Application | Farm, distributor, retail, export | Breakage rate and logistics distance | Export and long-haul routes need better compression strength |
The egg tray market growth drivers are not identical across regions, but three forces appear repeatedly: population growth, poultry sector formalization, and the need for affordable protective packaging. In Africa, demand is tied to local egg production expansion and replacement of informal transport methods. In Asia, scale is driven by high-volume poultry systems, dense logistics networks, and recurring demand from large hatcheries and distributors. In Latin America, organized distribution, export-oriented agribusiness, and better recycling loops are increasing the use of molded fiber packaging.
Africa’s egg tray demand is rising where poultry producers are moving from loose handling to standardized trays for distribution. This is important because longer haul times, weaker road infrastructure, and temperature variability increase breakage risk when eggs are not stabilized. Buyers in this region often prioritize trays that are inexpensive, easy to store, and compatible with locally available recycled fiber.
Asia contributes the largest base of demand because poultry production and egg consumption are already deeply industrialized in many countries. That scale creates strong repeat demand for 30-cell trays, stackable formats, and machines that can run multiple output sizes without frequent changeover. For converters and equipment buyers, the most important metric is not only tray cost, but also output per hour, pulp recovery rate, and labor requirement per production shift.
Latin America is supported by more organized feed supply, expanding supermarket channels, and more formal wholesale distribution. Egg trays here are often purchased for consistent performance across regional transport routes, where distributors want lower damage rates and predictable pallet stacking. That makes the market attractive for suppliers that can provide stable tray dimensions, moisture control, and repeatable compression properties.
Procurement teams are increasingly comparing tray material choices against unit cost, breakage reduction, and sustainability targets. In many cases, recycled fiber trays are selected because they reduce packaging cost per egg while supporting waste-paper recovery systems. This is also why sustainable packaging in developing regions is becoming a practical purchasing criterion rather than a branding issue.
A useful egg tray market comparison starts with the relationship between material type and distribution environment. The correct choice depends on whether trays move from farm to local market, from distributor to retailer, or through export channels. Buyers who only compare tray price often miss the larger cost driver: the cost of egg damage, rejected loads, and packaging replacement frequency.
| Comparison Factor | Molded Pulp | Plastic Tray | Foam / Alternative Materials |
|---|---|---|---|
| Purchase cost | Lower in many local markets | Higher upfront | Varies, often higher |
| Recyclability | Strong where fiber recovery exists | Reusable or recyclable depending on system | Often weaker |
| Shock absorption | Good for egg protection | Moderate | Variable |
| Export handling | Common in bulk shipments | Used in repeated-use systems | Limited in many markets |
| Best use case | Farm-to-distributor flow | Reusable internal logistics | Niche or specialized needs |
For small and mid-sized buyers, the decision is often less about technical novelty and more about cash flow, tray turn rate, and local collection systems. That is why the egg tray market for small poultry businesses usually favors molded pulp or recycled paper trays that can be purchased in batches aligned with weekly production. Larger distributors, by contrast, may evaluate hybrid models, reusable tray systems, and regional sourcing contracts.
The egg tray market works through a chain that usually includes fiber collection, pulp preparation, tray forming, drying, quality inspection, packing, and distribution. In a typical setup, recycled paper is converted into molded pulp, then pressed into tray shapes, dried to controlled moisture levels, and stacked for shipment. The commercial value of the market comes from converting low-cost fiber into a packaging format that reduces breakage during handling and transport.
It works by matching local fiber input with local or regional demand for egg protection. Producers buy waste paper or pulp, form trays in molds, and sell them to farms, traders, hatcheries, and distributors. The market is sensitive to input fiber price, drying energy cost, and the distance between manufacturing sites and poultry clusters.
A production system is usually judged by hourly output, moisture consistency, reject rate, and energy use per batch. For example, buyers often ask whether a machine can hold steady tray dimensions across an operating shift, because size variation affects stacking, pallet loading, and egg fit. In supplier evaluation, delivery risk management matters as much as product performance because late equipment arrival can delay plant commissioning and cash recovery.
| Operational Metric | Why It Matters | Buyer Concern |
|---|---|---|
| Output per hour | Capacity planning | Can the line meet local demand? |
| Moisture control | Tray strength and drying time | Will trays deform in storage? |
| Reject rate | Material efficiency | How much waste is generated? |
| Energy use | Operating cost | What is the per-tray cost structure? |
| Dimensional consistency | Stacking and transport | Will trays fit standard cartons and pallets? |
The broader egg packaging market is not limited to the three priority regions, so buyers should also understand how demand behaves in North America, Asia-Pacific, Latin America, and MEA. North America tends to have more mature packaging systems, stricter consistency requirements, and a greater share of reusable or standardized logistics formats. Asia-Pacific remains the largest volume center, while Latin America and MEA show more uneven but often faster percentage growth from a smaller base.
This matters because supplier strategy changes by region. In mature markets, quality compliance and delivery risk are weighted heavily. In fast-growth markets, conversion speed, local sourcing, and lower capital intensity often have a stronger effect on adoption.
The procurement side of the egg tray market outlook is often underestimated. Suppliers need to think in terms of production stability, spare parts availability, and acceptance of local fiber inputs. Converters need to assess whether a tray line can handle mixed feedstock and still keep size tolerance within acceptable limits.
Poultry operators, by contrast, usually focus on three numbers: breakage rate, storage density, and total cost of ownership. That is why the buying process often changes when a farm grows from direct-to-market sales into regional distribution. At that point, tray quality, stacking behavior, and supply continuity become more important than the lowest initial price.
A practical evaluation should cover quality compliance, delivery risk management, and total cost of ownership. Quality compliance includes tray dimensions, drying performance, and material uniformity. Delivery risk management includes lead time, spare parts availability, installation support, and the ability to begin production within a planned commissioning window.
For TCO, buyers should compare not only machine price but also labor load, energy use, mold replacement, reject rates, and maintenance frequency. A machine with lower purchase price can become more expensive if it needs frequent downtime or produces inconsistent tray weights. This is where suppliers with documented production experience and regional support structures can create measurable procurement value.
The best material depends on the distribution model and local recycling system. In many African, Asian, and Latin American markets, molded pulp is the leading option because it is low-cost, widely accepted, and suitable for bulk egg handling. Plastic works better in reusable logistics systems, but it generally requires better reverse logistics, cleaning, and higher upfront capital.
For buyers comparing egg tray market alternatives, the material decision should be linked to route length and handling intensity. Short farm-to-market routes can tolerate simpler trays, while long-haul or export flows usually require better compression resistance and more controlled dimensions. If the region has strong waste-paper supply, recycled fiber formats often produce the best balance between cost and recyclability.
| Scenario | Best Format | Why |
|---|---|---|
| Small poultry business, local market | 6/10/12-cell molded pulp trays | Low inventory pressure and simple handling |
| Mid-size distributor, multi-stop logistics | 30-cell molded pulp trays | Better density and stacking efficiency |
| Reusable internal transport system | Plastic trays | Lower replacement frequency |
| Export-oriented handling | Standardized fiber trays with strict tolerance | Better pallet stability and acceptance |
A practical egg tray market review for 2026 points to continued growth, but not uniform growth. Regions with faster poultry formalization will likely see stronger demand for standardized packaging, while areas with limited logistics infrastructure will continue to prefer low-cost molded pulp trays. The market is therefore split between volume-led growth and format-led improvement.
For manufacturers, this means product strategy should not be built on one tray size alone. A plant that can produce multiple formats and maintain stable drying and forming quality will be better positioned to serve farms, wholesalers, and distributors in different lanes. For buyers, the best result usually comes from matching tray type to route, not from choosing the cheapest available tray in isolation.
When buyers evaluate machinery partners, they often compare output range, automation level, mold compatibility, and maintenance needs. Rayee and similar companies are typically assessed on whether they can support both entry-level and scaled production models for different regional markets. In this category, the key issue is whether the supplier can deliver a full operating system, not just a forming machine.
A company profile from the company information source at https://www.eggtray-machinery.com is relevant because machine buyers usually need plant layout guidance, equipment selection support, and downstream process planning. That type of information matters in Africa, Asia, and Latin America, where electricity stability, fiber supply quality, and labor availability can differ sharply by site. The most useful suppliers are the ones that help align plant design with local procurement realities, rather than offering a single standard configuration for every market.
The egg tray market outlook: growth drivers across Africa, Asia, and Latin America remains positive because all three regions are expanding poultry consumption, modernizing logistics, and seeking cost-effective protective packaging. Africa is being shaped by local production growth and packaging substitution, Asia by industrial scale and repeat demand, and Latin America by structured distribution and export readiness. For manufacturers, this means opportunity exists not only in volume, but also in format specialization, local sourcing, and region-specific service models.
For suppliers, the strongest sales cases will come from equipment and tray systems that improve dimensional consistency, reduce waste, and keep operating costs visible before purchase. For poultry operators, the most practical strategy is to align tray format with route length, breakage tolerance, and inventory turnover. For converters, the best near-term opportunities are in recycled fiber systems that support affordable production while meeting the durability needs of local distribution.
The egg tray market outlook: growth drivers across Africa, Asia, and Latin America is favorable because demand is supported by three measurable forces: rising poultry output, broader egg consumption, and the need for lower-cost protective packaging. Across these regions, the market is not moving in one direction; it is splitting by material choice, tray format, and distribution channel. That is why the best decisions are operational, not speculative.
If you are a buyer, start by comparing tray formats against breakage rates, stacking efficiency, and local fiber availability. If you are a supplier or converter, focus on regional use cases in Africa, Asia, and Latin America rather than relying on a single global product model. If you are evaluating machinery partners, request output data, reject-rate targets, spare-part support, and commissioning timelines so the total cost of ownership is visible before purchase.
A: For most procurement use cases in these regions, molded pulp trays are the most practical choice because they balance low cost, shock absorption, stacking performance, and recyclability. Common options include 6-cell, 10-cell, 12-cell, and 30-cell trays. Small farms usually prefer lower-count trays, while distributors and wholesale buyers often choose 30-cell formats for better transport density.
A: The best material depends on route length, handling intensity, and local recycling conditions. Molded pulp is usually the best fit for farm-to-market and bulk distribution because it is economical and widely accepted. Plastic trays are more suitable for reusable internal logistics systems, while foam or other alternatives are generally used only for niche applications.
A: Buyers should evaluate output per hour, dimensional consistency, moisture control, reject rate, energy use, and the machine’s ability to handle locally available recycled fiber. It is also important to confirm installation support, spare parts availability, commissioning timelines, and whether the equipment can produce the tray counts your market actually needs.
A: Molded pulp remains the reference format in many developing markets because it offers a strong cost-to-performance balance. It is relatively low-cost, provides good egg protection, and works well where waste-paper recovery systems are available. For buyers, that usually means lower unit packaging cost and easier procurement alignment with local fiber supply.
A: The article indicates that suitable suppliers should offer technical fit, mold compatibility, and support for multiple output sizes, rather than a single fixed configuration. For buyers, the key question is whether the line can match required tray counts, local fiber input, and operating conditions in Africa, Asia, or Latin America while maintaining stable output and reasonable operating costs.
Hebei Rayee Egg Tray Machine Co., Ltd
+86 137 3108 3388
+86 157 3113 5928
Shijiazhuang, Hebei, China